Why should a fleet buyer in Lagos, Dubai, Jakarta or Bogotá care what the United States Environmental Protection Agency rules about truck exhaust? Because the American heavy-duty market is one of the three regulatory poles — alongside the EU and China — that sets the global product agenda for every truck manufacturer, including the Chinese EV truck industry we export from. When the US tightens its heavy-duty greenhouse gas standards, it changes what the world's drivetrain engineers work on, where the battery gigafactories point their output, how diesel residual values trend, and — more subtly — which zero-emission technologies get cheap enough, fast enough, to reach export markets. This article explains the US rulebook in plain terms (the EPA Phase 3 GHG standards and the state-level Advanced Clean Trucks mandates), then traces the five transmission channels through which American policy changes the options, prices and timing for EV truck buyers everywhere else.
The EPA regulates heavy-duty vehicle CO2 through the Clean Air Act, in phases. The current regime — the "Phase 3" greenhouse gas standards finalised in 2024 — covers model years 2027 through 2032 and works like this:
Under the Clean Air Act, California can set its own vehicle standards (with a federal waiver), and other states can adopt California's. The Advanced Clean Trucks (ACT) rule — adopted by California and a group of following states covering a large share of the US market — goes further than EPA's fleet-average approach: it is a sales mandate, requiring manufacturers to sell rising percentages of ZEV trucks in the covered classes (roughly 55% of vocational truck sales by 2035 under the original trajectory, with state-specific adoption timing). Alongside it, the Advanced Clean Fleets rule targeted fleet purchases directly, though its implementation has been contested and partially withdrawn — a reminder that this layer of US policy is politically contested and buyer-plans should track the litigation-and-revision cycle rather than any single headline.
| Instrument | Level | Mechanism | Status note |
|---|---|---|---|
| EPA Phase 3 GHG | Federal | Manufacturer fleet-average CO2, MY2027–2032 | In force; congressional-review attempts have recurred without resolution |
| Advanced Clean Trucks | California + adopter states | ZEV sales-percentage mandate by vehicle class | Adopted by multiple states; state-level political shifts have prompted some reconsideration |
| Advanced Clean Fleets | California + adopters | Fleet purchase/ZEV-milestone obligations | Core fleet mandates withdrawn/contested in California — monitor |
The takeaway for an international reader is not the US political blow-by-blow but the direction of the product ratchet: across federal and state layers, with varying speed, the world's second-largest truck market is being pushed toward ZEV vocational and tractor sales — and the manufacturing system is responding to that push in ways that reach every export market.
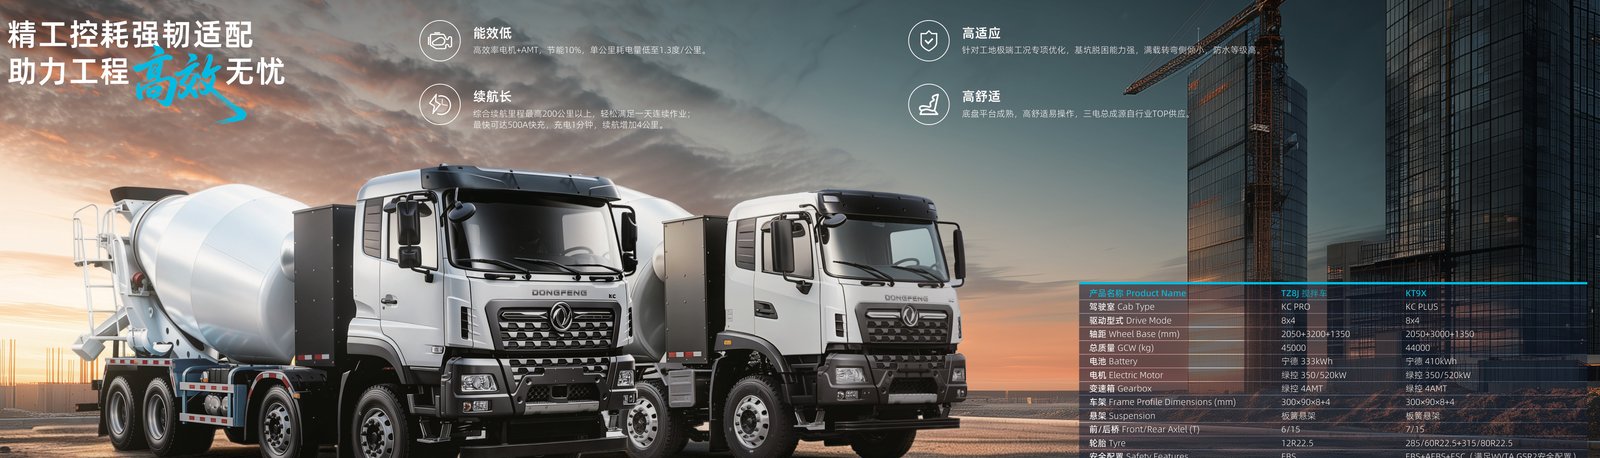
Chinese and global manufacturers building zero-emission vocational trucks — tippers, mixers, refuse trucks, the exact categories our export fleet covers — size their platform investments against the aggregate of EU, US and Chinese mandates. Every tightening of the US vocational ZEV expectations adds weight to the business case for the vehicle programmes that then also serve export duty. The KT-series sanitation and mixer EV trucks exist on a development curve funded by three regulatory poles at once; American rules are part of why the export product is arriving this mature, this soon.
US rules (together with the Inflation Reduction Act's manufacturing incentives on the industrial side) pull investment into North American battery capacity and keep global LFP demand on its steep growth curve. The consequence for export buyers is the continued decline in cell cost per kWh — the largest single line in an electric truck's bill of materials — and the availability of industrial-format LFP packs (the CATL architecture our trucks run) at prices that make 600 kWh mining trucks commercially rational. Whatever one thinks of US industrial policy, its gravity has helped bend the battery cost curve that every emerging-market fleet now benefits from.
Mandated ZEV fractions in the US and EU mean the world's two largest truck markets will be pushing large volumes of late-life diesel trucks into secondary markets through the late 2020s and 2030s. For buyers in Africa, Central Asia and Latin America this cuts both ways: cheap used diesel stock in the short term, and — as fuel prices, city access rules and corporate ESG requirements tighten — a growing stranded-asset risk on exactly those trucks. The fleets we advise are hedging: buying electric for the duty cycles that electrify cleanly, letting the used-diesel wave cover genuinely hard-to-electrify duty, and marking the diesel fleet's residual assumptions down accordingly.
US regulatory engineering travels: the test cycles, the credit-banking architectures, the telematics-based compliance verification, and increasingly the safety-adjacent requirements (mirroring the EU GSR2 stack we have covered separately) show up in Gulf SASO tender language, Latin American norms and multinational-miner fleet standards within a few years of their US debut. A buyer who understands the US rulebook is reading the draft of their own national requirements five years early.
The multinationals headquartered or listed in the US — mining majors, logistics groups, consumer-goods shippers — carry their home-market emissions expectations into every market they operate. When a US-listed miner demands Scope 1 haulage reductions from its Indonesian or Congolese contractors, that is US policy arriving at a mine gate by corporate channel. It is the single strongest driver of the electric mining-truck demand we are fulfilling in the nickel belt and the Copperbelt.
US heavy-duty rules will not put an electric truck in your yard — our job is that. But they have helped decide which electric trucks exist, how much battery they carry, what they cost, and how fast their diesel competitors depreciate. The global EV truck market is now a single connected system: a regulatory push in Washington accelerates a product curve in Wuhan, which improves the TCO of a mining fleet in Kolwezi, which tightens the tender scoring in Jakarta. Buyers who read the system — rather than just their local market — buy the right trucks, at the right time, on the right terms.
For an export-market fleet operator, tracking the US rule cycle is a 30-minute quarterly exercise, and it is worth doing systematically. Watch four indicators: the EPA's annual compliance data (manufacturer ZEV fractions and credit positions — the clearest read on how hard the industry is actually leaning); the roster of ACT-adopter states and any legislative reconsideration (state exits slow the mandate's effective scope, but no exit has reversed the manufacturers' product plans); the heavy-duty ZEV product announcements from the major OEMs (each new vocational ZEV platform validates the category and prices the global supply chain); and the used-diesel export flows from the US market (the leading indicator for residual-value effects in your own market). None of this requires an American policy analyst — the data is public, and the direction is legible. What it buys you is timing: the fleets that see the regulatory ratchet turning two years before their competitors buy their electric trucks at the improving end of the cost curve, and sell their diesel residuals before the wave lands.
Ready to electrify your fleet? Contact Shaanxi Fenghan Trading — authorized Dongfeng EV truck exporter. WhatsApp: +86 153 1943 1311 | Email: sales@fenghan-trade.com | dongfengevtrucks.com
🌐 Our Network: Fenghan Trade (SAGMOTO/SHACMAN Truck Export) · SAGMOTO heavy duty diesel trucks